Showing posts with label advice. Show all posts

Nilai jenama

Brand value - nilai jenama. Kenapa saya suka kopi tu, saya suka kereta ni. Jenama adalah penting demi kesinambungan sesuatu syarikat. Hanya mereka yang dilatih dalam "media brand reading" boleh merasai kepentingan carta sebegini.

MyETFUS50
2018

METFUS50 - 0827EA - 3Sep2018 - RM1.07 - MyETF-US50. 

Revisit selepas 3Sep2028. RM? 

Know your brokerage fee

Investing in shares must be done via brokerage, either you buy or sell, they take a cut irrespective of your gain or lose.

The big boys always had favourable fee structure from the brokerage house. It happen everywhere, in unit trust as well as share trading. Therefore, always go for the best rate.

Ask the brokerage with the high rates, what rate they give go the big boys?

Yes, you are the one that cross subsidized their profitability.

I am waiting for a fintech disruptor.....  

Kredit: redangpow.com

How much money you should have saved at every age

Hey planned for money to take care of you rather than you work for the money forever.

Here's how much money you should have saved at every age.

In your 20s:
Aim to save 25% of your overall gross pay, Greene tells CNBC. "That 25% is the combination of 401(k) withholdings, matching funds from your employer and any cash savings that you have," she notes. "It can also include debt repayment.

"Just make sure your lifestyle expenses don't exceed 75% of your gross income."

By age 30:
Have the equivalent of your annual salary saved, Greene says. If you earn $50,000 a year, aim to have $50,000 in savings when you hit 30.

Again, this includes any retirement account contributions, matching funds from your company, cash savings, or money you have invested elsewhere, in index funds or robo-advisers.

By age 35: Have twice your annual salary saved.
By age 40: Have three times your annual salary saved.

By age 45: Have four times your annual salary saved.
By age 50: Have five times your annual salary saved.

By age 55: Have six times your annual salary saved.
By age 60: Have seven times your annual salary saved.

By age 65: Have eight times your annual salary saved.

Greene's timeline is similar to the one recommended by retirement-plan provider Fidelity Investments, which says a good rule of thumb is to have the equivalent of your salary saved by age 30 and to have 10 times your final salary in savings if you want to retire by age 67.

Kredit: www.msn.com money


Please start today, please.

It pays to know your credit status via CCRIS or CTOS


I RELUCTANTLY signed up for a life insurance policy through a credit card issued by a finance company after repeated phone calls from the telemarketer. The policy was supposed to be for one year and a monthly instalment of RM33 would be charged to the credit card which had served me well for six years.

A year later, I found that RM33 was still being charged to my card monthly. When I called to ask about this, I was informed that I must write a formal letter to request that the charge be stopped. I was astonished because a verbal agreement over the phone was enough when they signed me up but now that I wanted to cancel, I must write a formal letter.

When the finance company was taken over by a bank, I decided to terminate the card. I went to one of the bank’s branches to get this done and specifically pointed out the monthly charge. The card was officially terminated and the insurance charge was automatically cancelled; at least that was what I was told.

A month later, I received a card statement with the amount of RM33 still being charged. I called the bank and was told the account was indeed terminated and I was assured that the statement was generated automatically by their computer system which was not yet updated.

The next month, I received another statement, this time showing that I owed RM66 on the card. I called the bank again and it was reiterated that my credit card had been terminated. I was also told to ignore the statement and that it needed a few months for the computer system to be updated.

Fast forward to almost a year and I was applying for a loan. There were problems getting my loan approved and when I checked, I found out they were due to an unsettled card account.

I went to the same branch of the bank and found out I had a credit debt of RM271.36, thanks to the monthly charges for the insurance policy that had not been terminated plus a penalty for late payment.

The bank denied any accountability but advised me to apply for a waiver, a process that would take a few months and I might still have to pay up in the end. So, to clear my credit list for my loan application, I paid the amount in full!

Learn from my experience. Never say yes to any credit card promotion over the phone.
Be alert for your credit status and check the Central Credit Reference Information System (CCRIS) or CTOS at least once a year.

AIMIR MA’ROF
Kuching


Hint: its easy to check your credit status, just go to BNM branches or AKPK branches, show your IC and get your free report. So easy!

These insurance companies get to sign up and charge you so easy meh, just agree via the phone BUT demand a letter from you to terminate, so double standard! The best way to get equal is to terminate the account or credit card that feed the payment, so that two accounts will be affected at once. When you do this, both company will generally need to spend 10 times more on marketing to gain you as their customer again. Silently teach them a lesson since we as a unit of customer can't win fighting them.

Do you remember the last case you win over them?   If they value you, they should treat you well.

credit-status
Cost of marketing a product is not cheap!


Is your unit trust doing well?

Most unit trust funds underperform the market

Kroijer points out that most unit trust funds have under performed the market in the last decade. “Almost 90% of the equity mutual funds globally have underperformed the market in the past 10 years (net of fees), based on numerous studies and reports. While some fund managers were able to beat the market, they still underperformed after deducting the fees (which include the sales charge and annual management fee),” he says.

According to the S&P Dow Jones Indices’ semi-annual report published in September, the S&P Indices Versus Active (Spiva) scorecard shows that as at June, 87.5% of the actively managed equity funds in the US underperformed its benchmark in the past decade. The Spiva Europe Scoreboard, which measures the performance of actively managed European equity funds, says 96% of the European funds underperformed their benchmark over a 10-year period as at the end of last year. According to the scorecard, European actively managed emerging market equity funds also suffered the same fate.

“There is a widely held belief that active portfolio management can be most effective in less efficient markets, such as emerging market equities, as these markets can provide managers the opportunities to exploit perceived mispricing. However, this view is not substantiated by our research as active funds underperformed their benchmarks in all time horizons, with 96% of funds underperforming the 10-year period,” says the report.

The fees imposed on investors are the main reason these funds underperformed the market, says Kroijer. Throughout his career, he has seen many investors pay huge amounts of fees to fund managers only to see their funds underperform the markets.

He says this is especially true in the hedge fund industry. “It was very hard to distinguish between the hedge funds that created value and those that did not when the markets consistently went up during those years. It was only during the huge declines of 2008/09 that many hedge fund managers found out that they had only been taking a long position on the market without adding much value.

“Of course, some of them made a huge amount of money by providing a little more value-add [but that did not justify the fees]. No wonder there were a lot of angry investors.”

Kroijer says hedge funds usually charge investors a 2% annual management fee and 20% of the total net profit. While the charges of unit trust funds are much lower than hedge funds, it is still not good enough as 9 out of 10 funds underperform the market net of fees, he points out.

The global equities index fund will provide you with diversification, compared with a single country ETF. For instance, if you only buy into the Malaysian index and it goes down by 50%, you will take a hit in your portfolio. But the global equities index fund as a whole may be unaffected.

Currently, there aren’t any global equity ETFs on Bursa Malaysia. But local investors can access them via overseas brokerage accounts.

Investors could look at the db x-trackers MSCI World Index UCITS ETF, which is listed on the Singapore Exchange, or the Infinity Global Stock Index Fund, which feeds into the Vanguard Global Stock Index Fund. The latter tracks the MSCI World Free Index, which comprises a basket of 1,600 stocks.

Investors could also look into the Vanguard Total World Stock ETF and iShares MSCI World Equity ETF, which are listed on the New York Stock Exchange.

> Lars Kroijer, author of Money Mavericks: Confession of a Hedge Fund Manager and Investing Demystified: How to Invest without Speculation and Sleepless Nights.
ekkamai-simplelife
See the dividends

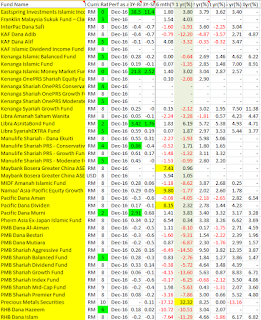
Thanks to Lars Kroijer for doing the research and confirming my hunch. Its simple, if the fund manager can't beat the average performance of EPF (EPF also weeding them out on yearly basis) or PNB, just liquidate and move on. Performance is everything because you are in the business of growing your own assets, not their assets. Look at the Dec16 performance table below and get the message. It really painful when the so called qualified professional lose your money on your behalf. Lose the money yourself, at least you gain the experience!
unit-trust-malaysia
1,2,3,5,10 yrs anualised performance

Hint: When the markets are badly down, look at their top holdings, if it is full of dividends paying company, hit the fund for a killing because market cannot be down all the time, it is a business as well here. Else who will pay for the managers salary! 

Stages of Collapse

An interesting excerpt from article sourced from cluborlov.

Stage 1: Financial collapse.
Faith in "business as usual" is lost. The future is no longer assumed resemble the past in any way that allows risk to be assessed and financial assets to be guaranteed. Financial institutions become insolvent; savings are wiped out, and access to capital is lost.

Stage 2: Commercial collapse.
Faith that "the market shall provide" is lost. Money is devalued and/or becomes scarce, commodities are hoarded, import and retail chains break down, and widespread shortages of survival necessities become the norm.

Stage 3: Political collapse.
Faith that "the government will take care of you" is lost. As official attempts to mitigate widespread loss of access to commercial sources of survival necessities fail to make a difference, the political establishment loses legitimacy and relevance.

Stage 4: Social collapse.
Faith that "your people will take care of you" is lost, as local social institutions, be they charities or other groups that rush in to fill the power vacuum run out of resources or fail through internal conflict.

Stage 5: Cultural collapse.
Faith in the goodness of humanity is lost. People lose their capacity for "kindness, generosity, consideration, affection, honesty, hospitality, compassion, charity" (Turnbull, The Mountain People). Families disband and compete as individuals for scarce resources. The new motto becomes "May you die today so that I die tomorrow" (Solzhenitsyn, The Gulag Archipelago). There may even be some cannibalism.

ECM by Princeton Economic

Stop paying the bare minimum on your credit cards!!!

Paying just the minimum on each card only prolongs the agony and increases the amount of total interest paid to your issuer. Save yourself over 20 percent in interest charges by fully paying off your credit card debt. Depending on your debt, you may add thousands to your wallet. Don't believe me? Try this Credit Card Calculator to see how many years it will take to pay off your balance based on your minimum payment. Results will shock you. Stop being a revolver to a card company.

Bank oh Banks

Ask any bank about their service, what they can give you and you'll get the feeling they are the best. Gee I got to tell you this....

Last week, on a weekday, I put my worn out jeans, t shirt and wear a slipper and started to walk around to find out who would be able to provide the best deal for my 300K home refinancing. When I bought this property, my god the banks are all out to win my heart to take their loan. But this time the experience, is totally different.

I walk into 3 foreign based bank (a standard one, cap payung and the rajin kut) and 3 local banks. Local bank as usual la, customer focused mentality is non existence. Sorry guys, I like to keep the money circulating in the country but who cares...

Of the three, the rajin is the one that stand out, immediately as I walk in someone is there to ask how could they help me. Wow.
At the standard one, I walk in slowly passing those nice working cubicles towards the counter at the end, no one care to ask. I pause, waiting and then I thought a nice environment is actually useless if the simple customer service is non existance. The one who really notice me, I guess is the armed security guard. Maybe I look like robbers kut!

Yeah from now on, I don't have preference for any bank brand. Go on you guy can spend million on air to say you do smile, great service, but today I proved to myself, it is all bluff.

My advice to the young people, if you need a loan press hard the staff for the best deal and ask them to compete and may the best win your account. Dont listen to their intimidation saying that you may not qualify.
After all, in any loan, the deal may take few weeks to settle and then you are expected to diligently pay them every month, aka work for the banks. Guess when do you hear from them again? Try to miss a few month repayment, I'm sure they want to talk to you again after so long...

FIVE DON'T - First

DON'T SLEEP WITH WATCH

Watches can emit a certain level of radioactivity. Though small, but if you wear your watch to bed for a long time, it might have adverse effects on your health.

MB: Give fatwa due respect

KOTA BARU: Muslims and Muslim non-governmental organisations (NGOs) should respect rulings or fatwa issued by the religious authorities, said Menteri Besar Datuk Nik Abdul Aziz Nik Mat.

He said they should set a good example by respecting such rulings, as only then would non-Muslims and non-Muslim NGOs not dare to protest against them.

"All fatwa are based on the Quran and sunnah (traditions of the Prophet) and for Muslims to protest against them is like going against the teachings of Allah. When Allah prohibits anything, it means that there is something bad or dangerous about it.

"If we go against it, that means we are breaking the law. Just like violating police or traffic laws. Are we that strong to go against Allah?

"Not only non-Muslims but also Muslims cannot protest against any fatwa," he said after launching the Kota Baru branch of the London Fish Tales restaurant yesterday.
He was responding to a demonstration in the city recently by non-Muslim NGOs to protest the National Fatwa Council's ruling on tomboyish behaviour.


Excerpt from NST


To my brothers and sister,

Please refrain yourself from making statements, comments regarding fatwa as fatwa are throughly discussed at congregation of ulamas. Ulama are group of people who has wide knowledge in their respective areas. If fatwa continued to be challenged, do you ready to be tested by god on a mass scale, tsunami scale of destruction for us? I dare not?

What they say...

Silver